Natiesha's Real Estate Blog

Homeowners Home Buyers Investors Home Sellers

Florida Property Taxes and Amendment 3: What South Florida Homeowners Need to Know

Oct 02, 2026

I get it. Property taxes are kind of a boring topic. But right now they are the hot-button issue in South Florida, and what happens on November 3 will show up on your tax bill. You've seen the headlines. You've seen the commercials. And maybe you're wondering how this will directly impact you and your family. I'm here to give you a quick breakdown so you can be better informed and make the best decision for your situation and your best interests. I'm not going to tell you how to vote. I am going to tell you what your property taxes do today, why Tallahassee wants to scale them back, and exactly what Amendment 3 says on the ballot. Why Florida homeowners already have it good Property taxes and homestead exemptions are a big deal in Florida, and other states don't have it as good as we do. We have no state income tax, and people have moved here specifically for our tax policies and the protections that come with them. If your Florida home is your primary residence, you already get three powerful benefits: Homestead exemption. It takes roughly $50,000 off your home's taxable value: $25,000 on all taxes, plus about $25,000 more on non-school taxes. Save Our Homes cap. Your assessed value can rise no more than 3% a year (or inflation, if lower), no matter how fast the market climbs. Portability. When you sell and buy another Florida homestead, you can carry up to $500,000 of your Save Our Homes savings with you. All of these are great, if you use them. Used well, they help you build financial security, wealth and a legacy for your family. Amendment 3 would not change the Save Our Homes cap or portability. It builds on top of the exemption. What your property taxes pay for today Property taxes are the main recurring income for your county, your city and your school district. Florida has no state income tax, so this is the money that runs the services closest to your front door. Schools. A large share of your bill goes to the school district. Amendment 3 leaves school taxes alone. Public safety. Police, sheriff, fire rescue and 911. Infrastructure. Roads, bridges, stormwater and flood protection. Quality of life. Parks, libraries, transit and after-school programs. Open your TRIM notice or tax bill and you'll see each of these listed line by line, with the amount you pay to each one. Note that fees like garbage and fire assessments are not property taxes, and no exemption reduces them. Why scale them back? The two sides Home values in Florida have climbed fast, and tax bills and local government budgets climbed with them. That is the heart of the debate. The Legislature put Amendment 3 on the ballot (House Joint Resolution 1F), and it needs 60% of the vote to pass. Supporters say homeowners need relief from rising bills, and local governments need a push to control spending. The governor, the Republican Party of Florida and Florida Realtors support it. Florida Realtors has launched a statewide Vote Yes on 3 campaign. In its own words, Florida Realtors supports Amendment 3 because "affordability doesn't end at closing. The ongoing cost of homeownership matters just as much as the cost of buying a home." The association says the measure helps Floridians stay in their homes and keep more of what they earn. It also says the lower 5% cap gives more stability to property owners and to the tenants and businesses who depend on them. Opponents say the money has to come from somewhere. State economists estimate local governments would collect about $4.9 billion less in 2027, growing to about $11.8 billion a year. The Florida Democratic Party, public safety groups, and many cities and counties oppose it. Florida TaxWatch, a nonpartisan budget watchdog, recommends a "no" vote. Here in South Florida, Miami-Dade County estimates a $385 million loss in the first year. Mayor Daniella Levine Cava has said roads, flood protection, parks, libraries and transit "could all face difficult cuts." Closer to home, the Miramar Pembroke Pines Regional Chamber of Commerce opposes Amendment 3. The chamber says it supports property tax relief for homeowners, but that no plan exists to replace the lost local revenue. It warns the gap could lead to "higher sales taxes, increased millage rates on commercial properties, and expanded special fees" that land on Miramar and Pembroke Pines businesses, renters and consumers. Critics also point to tax shifting. If homesteads pay less, more of the load can fall on rentals, businesses and second homes, which can reach renters through higher rents. The exact wording on your ballot Here is what you will read in the voting booth on November 3, 2026. Ballot title: INCREASED HOMESTEAD EXEMPTION; LOWER CAP ON INCREASES IN NON-HOMESTEAD PROPERTY ASSESSMENTS. Ballot summary: This amendment increases the homestead exemption, for all non-school taxes, to $150,000 in 2027 and $250,000 in 2028, and adjusts for inflation thereafter. It requires the Legislature to prescribe a uniform procedure for counties and municipalities, for their respective levies, to increase the homestead exemption up to full assessed value, and allows special districts, subject to referendum approval, to do the same. Persons who are not Florida residents on December 31, 2026, will receive the existing homestead exemption upon qualifying for a homestead exemption, with the increased homestead exemption beginning with the fifth year of exemption, to the extent permitted by the U.S. Constitution. This amendment reduces the annual cap on assessment increases for non-homestead properties from 10% to 5%. This amendment requires counties and municipalities to use property taxes solely for public safety, education and schools, infrastructure, natural resources, bond debt service, retirement benefits for employees, and operations and administration. Other expenditures may be approved by county officers or county or municipal governing bodies unless prohibited by general law, notwithstanding Article VII, Section 9(a) of the Florida Constitution, which allows counties and municipalities to levy property taxes for their respective purposes. This amendment takes effect January 1, 2027. In plain English, it does four things: Raises the homestead exemption on non-school taxes to $150,000 in 2027 and $250,000 in 2028, then adjusts it for inflation. Cities and counties could later go further, up to the full value. Makes people who move to Florida after December 31, 2026 wait until their fifth year of homestead to get the bigger exemption. Cuts the yearly cap on assessment increases for non-homestead property (rentals, second homes, commercial) from 10% to 5%. Limits what cities and counties can spend property taxes on, with room for local officials to approve other spending. What it could mean for you The impact depends on who you are. If it passes, the first tax bills to reflect it arrive in November 2027. If you are... What Amendment 3 would likely mean A homesteaded homeowner A lower bill on the non-school portion. Florida TaxWatch estimates average savings of about $1,035 in 2027 and $2,085 in 2028. School taxes stay the same. An owner whose assessed value is under $250,000 Possibly no non-school property tax at all by 2028. Many long-time owners protected by Save Our Homes fall here. A buyer already living in Florida The full exemption once you homestead your new home. Moving to Florida in 2027 or later Today's exemption for your first four years, then the larger one in year five. An investor or landlord No larger exemption, but your assessment could rise only 5% a year instead of 10% on non-school taxes. Watch for tax rates shifting toward non-homestead property. A renter No direct savings. Your rent could feel it if your landlord's taxes rise. Everyone shares the other side of the ledger: whatever your city and county decide to cut, or charge for in other ways, to make up the difference. Before you vote A lower tax bill sounds great, and for many homeowners it would be real money. The question worth a little thought is what you get, and what you give up, in return. Pull out your TRIM notice and find your non-school taxes. That is the part Amendment 3 touches. Ask your city and county what they would cut or change if it passes. Check that your homestead exemption is filed. None of these benefits help you if you haven't claimed them. Read the amendment for yourself on your sample ballot from the Supervisor of Elections. Whichever way you vote, vote informed. And if you want to know what this means for your home, your next purchase or your investment property, reach out. I'm happy to walk through your numbers with you. This post is for general education and is not tax or legal advice. Talk with your tax professional or your county property appraiser about your specific situation. Sources Florida Chamber: Florida's 2026 Property Tax Amendment 3 (ballot title, summary, fiscal impact) Florida TaxWatch: Taxpayer's Guide for the 2026 Constitutional Amendments Pinellas County Property Appraiser: Amendment 3 FAQs Florida Phoenix voter guide: Amendment 3 CBS Miami: Miami-Dade warns of $385M revenue loss Florida Policy Institute: Amendment 3 ballot language and local fiscal impacts Tax Foundation: analysis of the Florida property tax proposal Miramar Pembroke Pines Regional Chamber of Commerce: Amendment 3 position Florida Realtors: Amendment 3 advocacy page Florida Realtors launches Vote Yes on 3 campaign

Read More
Homeowners Home Sellers Investors

Rainy Season Is Exposing Roof Problems in Pembroke Pines and Miramar — Here's What to Watch For

Sep 21, 2026

In Pembroke Pines, Miramar, and across South Florida, rainy season has a way of revealing home maintenance issues homeowners may not notice the rest of the year. A small ceiling stain suddenly grows. A tiny drip appears near a window. Moisture starts showing up where everything once seemed fine. Often, the roof has been trying to warn you for a while. As a Realtor® and renovation-minded real estate professional serving Pembroke Pines and Miramar, I've seen firsthand how roofing issues quietly impact more than comfort and safety — they affect property value, insurance eligibility, and resale potential too. The good news: most major roofing problems start out manageable, if you catch them early. Small Signs Can Point to Bigger Problems Many homeowners don't realize roofing problems usually start subtly. Some early warning signs to watch for: Ceiling discoloration Peeling paint Musty or moisture smells Lifted shingles or cracked tiles Clogged gutters Water intrusion near doors or windows These issues might seem minor in dry weather, but South Florida's rainy season exposes weaknesses fast. What starts as a small repair can turn into water damage, mold concerns, or interior deterioration if it's ignored too long. Roof Age Matters More Than Ever in South Florida Roof age has become one of the most important factors for homeowners in Pembroke Pines and Miramar to understand. An older roof can affect: Insurance eligibility Insurance premiums Buyer confidence Financing options during resale Even when a roof isn't actively leaking, buyers and insurers pay close attention to its remaining lifespan. Knowing your roof's condition before problems arise puts you in a much stronger position — whether you're staying put or planning to sell. Deferred Maintenance Gets Expensive Quickly One of the most common things I see with Pembroke Pines and Miramar homeowners is waiting until there's visible interior damage before addressing roofing concerns. Unfortunately, once water gets into the home, repairs become significantly more expensive. Preventative maintenance is almost always far more affordable than emergency restoration. Simple steps like: Roof inspections Gutter cleaning Sealing vulnerable areas Replacing damaged materials can extend your roof's life and reduce the size of repair bills down the road. Your Roof Protects More Than Your House A roof does more than cover a property — it protects your finances, your comfort, your belongings, and your home's long-term value. In South Florida, where heavy rain and storms are simply part of life, staying proactive matters. Your home may already be giving you subtle warnings before a bigger issue develops. The key is paying attention now, before rainy season turns a small concern into a major one. Thinking about your roof's condition — or what it might mean for your home's value if you're planning to sell in Pembroke Pines or Miramar? Let's talk. I combine local market knowledge with a renovation background to help homeowners protect and maximize their home's value. Book a free consultation.

Read More
Homeowners Investors Home Sellers

World Cup Fever: What the 2026 FIFA World Cup Means for South Florida Real Estate

Aug 07, 2026

What a summer it was! For more than a month, South Florida had World Cup fever. Flags hung from car windows, jerseys filled every grocery store, and watch parties popped up everywhere, from Miami's waterfront to our own backyard here in Miramar. Whether you were cheering for Brazil, Colombia, Cape Verde, Haiti, the USA, or all of the above, everyone felt it. And while restaurants, hotels, and shops were the obvious winners, the World Cup may leave a longer-lasting mark on South Florida: on the people who came to visit and started wondering what it would be like to live here. South Florida on the World Stage Hard Rock Stadium in Miami Gardens hosted seven FIFA World Cup matches in 2026, including: Group stage: Saudi Arabia vs. Uruguay, Uruguay vs. Cape Verde, Scotland vs. Brazil, and Colombia vs. Portugal Knockout rounds: a Round of 32 match, a quarterfinal, and the third-place "Bronze Final" on July 18[1] Downtown, the FIFA Fan Festival at Bayfront Park brought fans together to watch matches on giant screens.[2] It wasn't Hard Rock Stadium's first time in the global spotlight. It has hosted Super Bowls, the Formula 1 Miami Grand Prix, and the opening match of the 2025 FIFA Club World Cup. But few events bring in fans from as many countries as the World Cup. Miami Gardens, which grew from the neighborhood once known as Carol City into its own city in 2003, has worked hard to make sure the world knows these games happen in Miami Gardens, not just "Miami." Local leaders have also been approving new hotels to capture more of this tourism in the future.[3] World Cup Fever in Miramar Here in Miramar, the excitement came home. The city hosted free World Cup watch parties at the Miramar Regional Park Amphitheater on June 19 and June 27, with the big screen, local food vendors, and thousands of fans cheering together.[4] That June 27 watch party fell on the same night Colombia played Portugal just down the road at Hard Rock Stadium. With watch parties across Broward and Miami-Dade, and fans filling local restaurants, the tournament showed off exactly what makes our community special: diverse, multicultural, and passionate. The Real Estate Angle: The World's Biggest "Test Drive" Big events like the World Cup give visitors something no brochure can: a firsthand experience of daily life here. Visitors staying in the area didn't just see the stadium. They drove through our neighborhoods, ate at local restaurants, shopped at our stores, and experienced the sunshine, the culture, and the convenience of places like Miramar and Pembroke Pines. Many got to see: The location: Miramar and Pembroke Pines sit right between Fort Lauderdale and Miami, minutes from Hard Rock Stadium, with easy access to I-75 and Florida's Turnpike. The lifestyle: parks, family-friendly neighborhoods, great food, and year-round outdoor living The culture: communities where Caribbean, Latin American, and international families feel right at home The value: more space and more home for the money than many coastal areas For some visitors, that "test drive" plants a seed: "What if we lived here?" That's often how relocation starts. Not with a listing, but with an experience. Who Might Be Looking at South Florida Now? International fans and families from Latin America, the Caribbean, and Europe who fell in love with the area Remote workers who realized they could work from somewhere with sunshine and soccer Investors watching South Florida's global profile and its growing hotel and event infrastructure Former residents who came back for the games and remembered why they loved it here What It Means for Buyers, Sellers, and Investors An honest note: Big events bring a burst of visitors and spending, but economists disagree on how much lasting economic benefit they create.[5] The World Cup alone doesn't set home prices. Interest rates, insurance, inventory, and local conditions still matter most. But global exposure, a strong community reputation, and more people considering South Florida can all help support demand over time. For sellers: Visitors from around the world just got a firsthand look at our area. Well-prepared homes that show off South Florida living, like outdoor spaces, updated interiors, and hurricane-ready features, make a great first impression on buyers relocating from out of the area. My Eden Styled-to-Sell System is designed to help your home stand out. For buyers: If the World Cup made you fall in love with South Florida, you're not alone. Start with my Ultimate Relocation Guide and let's explore neighborhoods that fit your life. For investors: Areas near major event venues can see strong short-term rental demand during big events. But check city rules and HOA restrictions first, since many communities limit short-term rentals. See the Master Investor Series. The Fever May Fade, But the Love for South Florida Stays The final whistle has blown, but the memories, and maybe some new neighbors, will stay. South Florida showed the world what we already know: this is a vibrant, diverse, welcoming place to live. Thinking about making South Florida home, or selling to someone who just fell in love with it? Book a free consultation, and let's talk about your next move. This article is for informational purposes only and is not financial or investment advice. Sources CBS News Miami: World Cup Matches at Hard Rock Stadium FIFA: Fan Festival Miami WLRN: How Miami Gardens Has Capitalized on Hard Rock Stadium City of Miramar: World Cup Watch Party Axios Miami: World Cup Economic Impact

Read More
Investors

Real Estate Investors Roundtable: Million-Dollar Lessons

Jun 08, 2026

What Are the Most Expensive Mistakes Real Estate Investors Make? Most real estate investors don't lose money because they lack ambition. They lose money because they make decisions without having all the information they need. Sometimes it's buying the wrong property. Sometimes it's underestimating renovation costs. Sometimes it's holding onto a property far longer than they should. As both a real estate investor and REALTOR®, I've seen firsthand how small mistakes can create big consequences—and how the right strategy can completely change the outcome. Over the years, I've been involved in property renovations, buy-and-hold investments, short-term rentals, and helping investors evaluate opportunities throughout South Florida. One thing I've learned is that the most valuable lessons often come from mistakes—whether they're our own or someone else's. That's why our next REI Roundtable is focused on Million-Dollar Lessons from Real Estate Investing Mistakes. During this interactive discussion, we'll explore some of the common pitfalls investors face and the lessons that can help them make more informed decisions moving forward. Whether you're thinking about purchasing your first investment property or you're actively growing a portfolio, this conversation is designed to help you think strategically about your next move. Join Us REI Roundtable: Million-Dollar Lessons from Real Estate Investing Mistakes Wednesday, June 17, 2026 1:00 PM – 2:00 PM Online Event I look forward to seeing you there and hearing your own investing lessons along the way.

Read More
Homeowners Investors

From Underperforming Property to Wealth Builder: When It's Time to Let Go

May 15, 2026

Not every property is a good property forever. That may sound surprising coming from a real estate professional, but it's one of the most important conversations homeowners and investors need to have. Sometimes a home or investment property that once served you well can quietly become an underperforming asset. Maybe it needs more maintenance than it should. Maybe the rent no longer keeps pace with expenses. Maybe the location no longer supports your long-term goals. Or maybe too much of your equity is just sitting there. Holding onto a property simply because you've owned it for years can sometimes cost more than letting it go. The Cost of Staying Comfortable One of the biggest financial traps I see is what I call equity stagnation. A property may have appreciated significantly over time, but if that equity isn't being used strategically, it may not be working as hard as it could for you. For homeowners, this may mean staying in a home that no longer fits your lifestyle. For investors, it may mean keeping a property with low returns while better opportunities exist. The real question isn't: "Have I owned this for a long time?" The better question is: "Is this property still aligned with my financial goals?" Signs It May Be Time to Reposition Some common signs: Rising maintenance costs Below-market rental income Too many management headaches Weakening demand for your property type or area Large amounts of untapped equity Better opportunities in another property type or location In South Florida, watch these closely too: Insurance premiums that keep climbing, especially on older homes with aging roofs HOA fees that rise faster than your rent Condo special assessments tied to Florida's newer building safety requirements These costs can quietly turn a once-profitable property into one that barely breaks even. Sometimes selling isn't about walking away. Sometimes it's about leveling up. Letting Go Can Be a Growth Strategy I often remind clients that selling an underperforming asset isn't a loss. It can be a strategic move toward something stronger. For example, selling one high-maintenance single-family rental may let you reposition into a duplex, a small multifamily property, or a better-performing market. For investors, a 1031 exchange may let you make that move while deferring capital gains taxes. Learn how in Master Investor Series | Part 4 of 5: Unlocking Wealth with 1031 Exchanges. For homeowners, the home-sale tax exclusion can let you keep up to $250,000 of profit tax-free, or $500,000 for married couples, if you qualify. Florida's Save Our Homes portability may also let you carry part of your property tax savings to your next Florida home. See Home-Related Tax Deductions. The goal isn't simply to own property. The goal is to build wealth intentionally. Or... Reposition in Place Letting go isn't the only option. Sometimes an underperforming property just needs a strategic upgrade to perform again: updating a dated rental so it commands higher rent, adding value before a sale, or making hurricane-ready improvements that lower insurance costs. With my renovation background, I help clients compare all the paths: Hold as is Improve and hold Improve and sell Sell and reinvest The right answer depends on the numbers, and on your goals. See also: Renovate or Relocate? 3 Questions To Help You Decide. Think Beyond the Current Property Sometimes the most valuable question you can ask is: What else could this equity do for me? Could it: Reduce debt? Fund a better investment? Improve your cash flow? Support a move that better fits your life? Real estate should support your life and your wealth-building goals. If it no longer does, it may be time to consider the next chapter. Sometimes letting go is exactly how growth begins. Wondering if your property is still pulling its weight? Let's run the numbers together. Book a free consultation, find out what your property is worth, or visit Invest With Natiesha. This article is for informational purposes only and is not tax, legal, or financial advice. Consult a qualified tax professional before selling or exchanging property.

Read More
Investors Home Sellers Home Buyers Homeowners

I Was Selected for the eXp Florida Agent Advisory Council. Here's What That Means for You

May 10, 2026

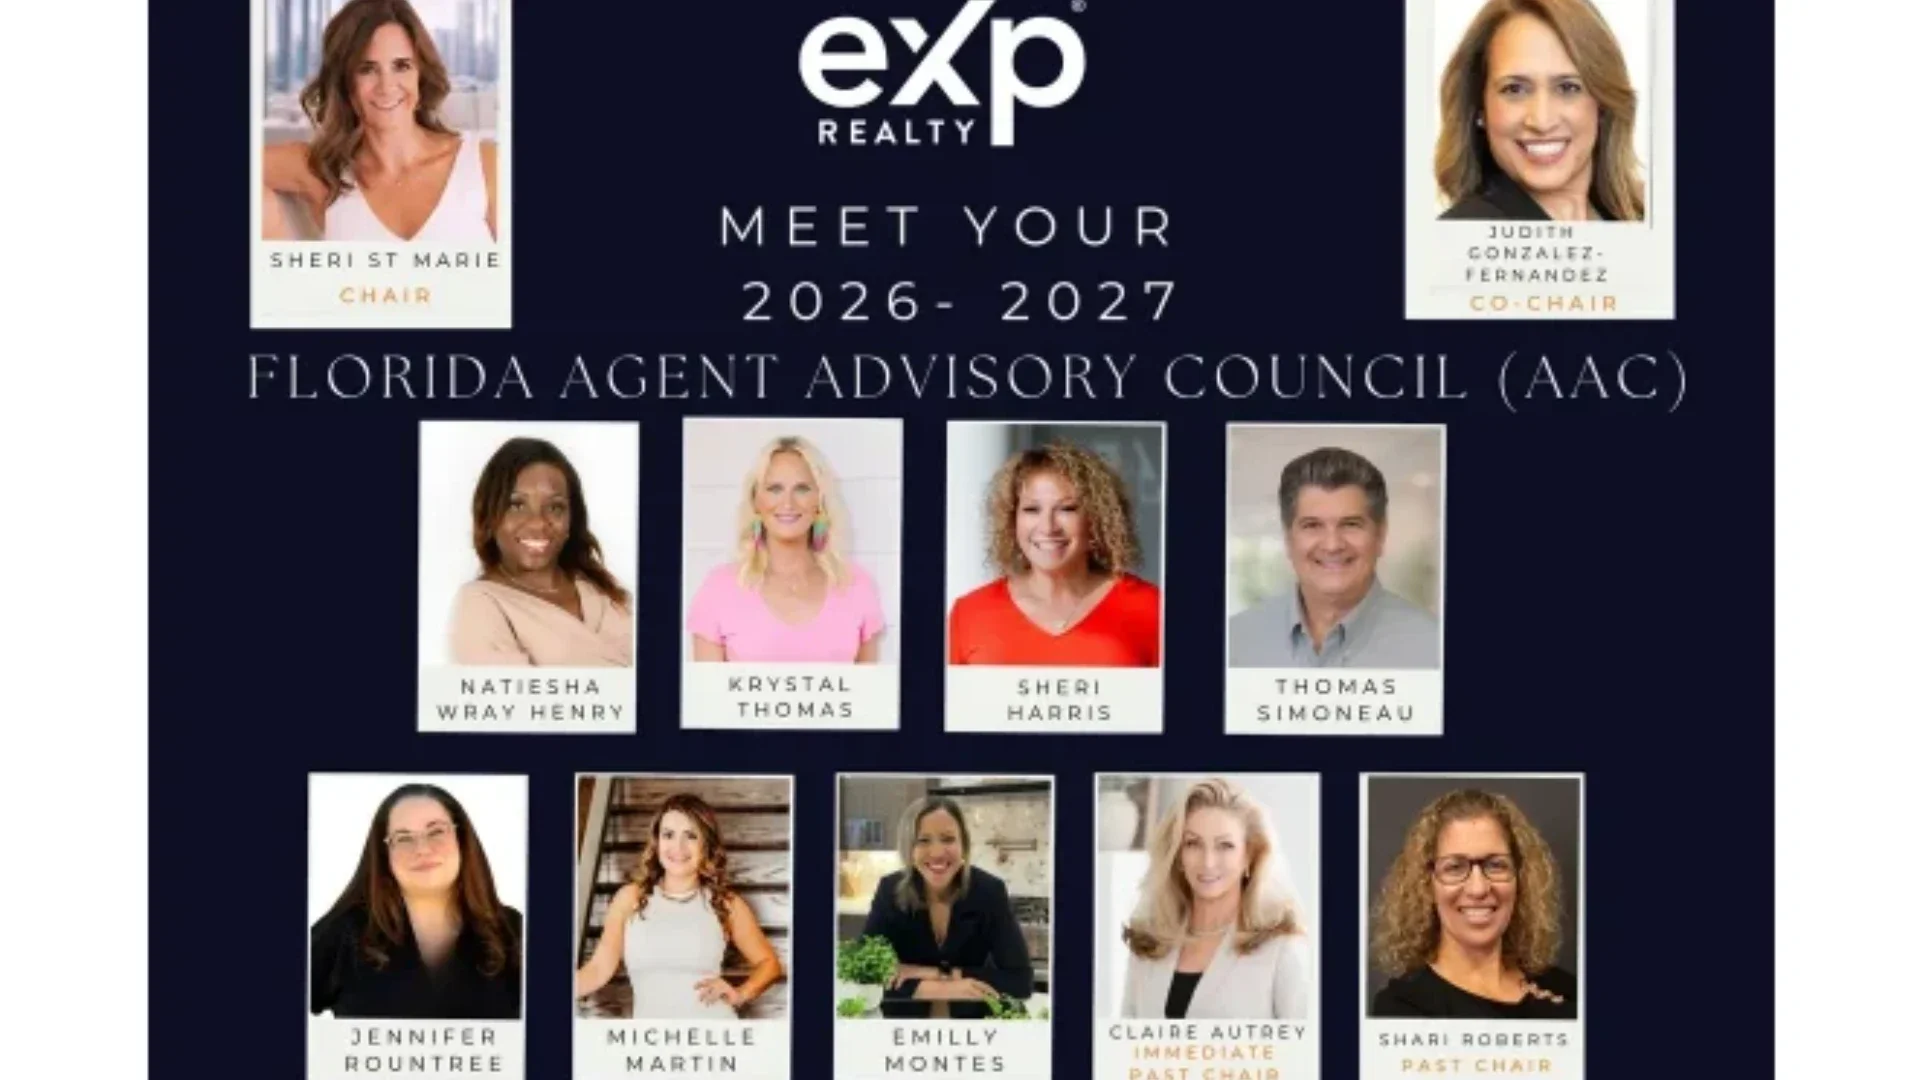
I have a confession. When I was selected for the 2026-2027 eXp Florida Agent Advisory Council, I said yes before I fully understood what I had been chosen for. Then I looked at the numbers. I was selected to represent more than 8,000 eXp agents across Florida, chosen from a pool of highly qualified top agents around the state. Eleven of us are on this year's council. So yes, I figured out what a great honor it was after the fact. I am laughing at myself a little, and I am also deeply grateful. What is the Agent Advisory Council? The Agent Advisory Council, or AAC, is a small group of working agents who act as a united agent voice alongside eXp's Florida state team. Agents apply once a year, and the council chairs and state leadership review the applications. Members serve two-year terms. We meet monthly, and the work is practical: Giving the state broker team and eXp leadership honest feedback from the field Shaping training and education built for Florida agents Weighing in on new systems and processes, and sometimes testing new tools before they roll out Planning the events that bring Florida agents together in person Staying connected with eXp's national Agent Advisory Council That matters at a brokerage like eXp. We don't gather in one office building. We are spread across every corner of Florida, so leadership depends on agents who will speak up honestly on behalf of their colleagues. Why I said yes Here is the honest truth. I applied without knowing much about the council. What I did know was that I wanted to have a voice, and I wanted to help new agents. I have a heart for agents who are just starting out. They want to learn this business, but they are scared, because real estate is intimidating in the beginning. It is a tough business. And if you are like me, a mom with kids, it can feel daunting. I want those agents to have hope. There is room for us. There is room enough for all of us to be successful. Once you find your niche and the way you want to work, you can exceed what you even thought was possible. That is my big why. It is the same reason I spent 17 years in the classroom with Miami-Dade County Public Schools, the same reason I mentor newer agents as an eXp Certified Mentor, and the same reason I host the REI Roundtable for our local investor community. The council lets me do that for my colleagues across the whole state. You can read more of my story on my About page. What this means if you are my client Fair question. You are hiring me to sell your home or help you buy one, so here is why a council seat matters to you. I hear what is happening across Florida. I sit in conversations with agents from every part of the state. I learn early how buyers are behaving, what is slowing closings down, and how issues like insurance and property taxes are playing out in other markets. That shapes the advice I give you about your home in Miramar or Pembroke Pines. I have a stronger network behind you. If you are relocating within Florida, or your buyer is coming from another city, I likely know a trusted agent there. Good relationships between agents make transactions go more smoothly. I am held to a high standard. My peers and my brokerage are trusting me to represent them. I bring that same care and accountability to every client, whether you are selling, buying, or investing. What does not change is how I work. I am still the renovation-savvy advisor who will walk your home with you and help you understand what you have, what it could be, and what makes financial sense. My Eden Styled-to-Sell System is still how I prepare, style, and launch a listing. And my clients' own words are still the recognition I value most. Thank you To the colleagues and leaders who selected me: thank you for your confidence. I plan to earn it. To my clients, past and present: you are the reason I have anything worth bringing to that table. Every home we have prepared, every negotiation, and every closing taught me something I now get to share. If you are a fellow agent and curious about what it is like to work at a brokerage where agents have a real voice, I am happy to talk. You can learn more about joining eXp here. And if you are a homeowner in Miramar or Pembroke Pines wondering what your next move should be, let's start with the numbers. Get your instant home valuation, or contact me to set up a conversation. Natiesha Wray Henry is a REALTOR® with eXp Realty serving Miramar, Pembroke Pines, and South Florida. She is an eXp Certified Mentor and a member of the eXp Florida Agent Advisory Council.

Read More
Investors Homeowners Home Sellers Home Buyers

From Frustration to Fulfillment: My Conversation on the Beyond the Velvet Rope Podcast

Mar 11, 2026

Recently, I had the opportunity to sit down with my coach, Neal Oates Jr., on his podcast, Beyond the Velvet Rope, for a conversation that was both personal and meaningful to me. The episode is called "From Frustration to Fulfillment," and it gave me the chance to share parts of my journey that many people don't see behind the scenes: the doubts, the risks, the growth, and the moments that shaped the path I'm on today. 🎧 Listen to the episode here A Journey That Started With a Leap of Faith Before real estate, I spent 17 years as a public school educator with Miami-Dade County Public Schools, teaching English, reading, and business, and teaching ESOL to adults who were building new lives in this country. Teaching was meaningful work, but deep down, I carried a dream of building something of my own. That dream eventually led me to take a leap of faith that many people thought was risky: leaving the classroom to pursue entrepreneurship and real estate investing. At the time, it felt uncertain, and even a little scary. But looking back, that leap became the defining moment that shaped my determination, creativity, and belief in what's possible when you follow a vision. What We Talked About Neal and I had an honest conversation about growth, mindset, and the realities of building something meaningful. We talked about: My transition from educator to entrepreneur The birth of Eden Estate Enterprises, and the challenges and lessons of my first real estate projects How I developed my Eden Styled-to-Sell System The mindset shifts that helped me keep going through difficult moments The role of mentorship, accountability, and strong professional networks Holding non-negotiable standards and values in business Why frustration can be the starting point for fulfillment Building a Life and Business With Purpose Today, my work in real estate is about more than buying and selling homes. It's about helping people see possibilities, whether through homeownership, strategic property improvements, or real estate investing. Real estate has allowed me to combine creativity, strategy, and service, and I'm grateful for every lesson along the way. The educator in me still shows up every day, in the homebuyer workshops I present, the Real Estate Investors Roundtable I founded, and the way I guide every client through their decisions. This conversation reminded me how powerful it can be to share our stories: not just the wins, but the journey that leads to them. Listen to the Full Episode If you're navigating a career change, exploring entrepreneurship, or simply curious about the mindset behind building something meaningful, I hope this conversation encourages you. 🎧 Listen to the full episode here Let's Stay Connected If you're interested in real estate, investing, or how thoughtful property improvements can create opportunity, I'd love to connect. Learn more about me Explore the Eden Styled-to-Sell System Start the Master Investor Series Book a free consultation Natiesha Wray Henry, MBA REALTOR® | Investor | Property Transformation Strategist eXp Realty | Serving Miramar, Pembroke Pines & South Florida

Read More
Home Buyers Investors

Beyond the Mortgage: The True Cost of Owning a Home in South Florida

Jan 20, 2026

When most buyers figure out whether they can afford a home, they focus on one number: the monthly mortgage payment. It's what the lender qualifies you for, what everyone talks about during showings, and what sets the budget. But the average annual cost of owning and maintaining a single-family home in the U.S., not counting the mortgage, is estimated at about $21,400 in 2025. That's roughly $1,800 a month.[1] With those costs added in, a $2,500 mortgage payment can easily become more than $4,000 in total housing costs. Qualifying for a mortgage answers one question: "Can a bank trust you with this loan?" It doesn't answer the more important one: "Can you comfortably afford this lifestyle?" Nearly 45% of homeowners report regrets after buying, most often because maintenance and hidden costs were higher than expected.[2] The good news: most of that regret is preventable with the right plan. Here's the full picture, with what's different here in South Florida. The Predictable Ongoing Costs Property Taxes Nationally, the average property tax bill reached $4,271 in 2024, and many homeowners saw increases of 16% or more.[3] Even when tax rates dip, rising home values keep bills climbing. The Florida property tax trap: Many buyers assume their taxes will match what the seller paid. They usually won't. If the seller has owned and lived in the home for years, Florida's Homestead Exemption and Save Our Homes cap have likely kept their taxable value well below market value. When you buy, the home is reassessed at close to its current market value, so your first full tax bill can be much higher. Always estimate taxes based on your purchase price, not the seller's bill. Then, once you move in, apply for your own Homestead Exemption by March 1 to lower your bill and cap future increases on your primary home. Homeowners Insurance Nationally, the average premium for a new policy rose 8.5% year-over-year as of December 2025.[4] In South Florida, premiums are typically far higher than the national average because of hurricane risk. You may also need separate flood insurance, depending on the property. What drives your premium here: the roof's age and type, impact windows and doors, the home's age, and wind mitigation features. Two homes at the same price can have very different insurance costs, so get insurance quotes before you make an offer. See 6 Strategies to Save on Home Insurance Premiums. Watch your escrow. If taxes or insurance rise, your lender adjusts your escrow account, and your monthly payment can go up $200–$300 in a single year without you doing anything. HOA and Condo Fees About 40% of homes for sale nationally have HOA fees, with a median around $125 a month. Single-family homes often run $200–$300.[5] In South Florida, many communities have HOAs, and fees vary widely. Condo buyers, take note: Florida's newer condo safety laws require structural inspections and fully funded reserves in many older buildings. That has led to higher monthly fees and special assessments in some associations. Before you buy, review the association's budget, reserves, and any planned assessments. Utilities In 2024, energy and utility costs averaged $4,494 a year, plus about $1,515 for internet and cable.[1] In South Florida, air conditioning drives a big share of electric bills, especially in summer. Buyers moving from an apartment to a house often see utility costs roughly double. Routine Maintenance and Services Lawn care, pest and termite control, pool service, AC servicing, and pressure washing are practical necessities here. Together they can add $200–$400 a month. The Irregular, But Inevitable, Expenses Major System Replacements Repairs aren't a matter of if but when. Home maintenance now averages about $8,800 a year, and first-year owners often spend more.[1][6] Typical national costs: AC replacement: $5,000–$10,000 Roof replacement: $8,000–$15,000 nationally, and often much more in South Florida, especially for tile roofs Water heater: $1,200–$2,500 Plumbing updates: Many older South Florida homes have cast iron drain pipes, which can be costly to repair or replace as they age Use your inspection as a budget roadmap. A 15-year-old water heater or an aging roof isn't necessarily a deal-breaker, but it signals likely expenses in your first few years. Buyers who understand these timelines can plan instead of scramble. And newer homes aren't maintenance-free; systems still age, and warranties expire. Emergencies also have terrible timing: an AC failure in August, a roof leak during rainy season, or storm damage after a hurricane. Without cash reserves, one emergency can derail your finances. With my renovation background, I help buyers read inspection reports as a budget plan, estimating what each system will cost and when. Costs That Creep Up Over Time Here's what surprises many first-time buyers: the "fixed" costs of homeownership aren't fixed. A fixed-rate mortgage locks in your principal and interest, but taxes, insurance, HOA fees, utilities, and maintenance can all rise. Picture this: a letter arrives saying your payment is going up $200 a month because insurance premiums rose and your home was reassessed. Nothing changed on your end, yet your housing costs just went up $2,400 a year. Plan for these costs to rise about 3–5% a year. True stability comes from planning for change. Planning Smarter: How to Stay Ahead 1. Create a dedicated home repair fund. Keep it separate from your emergency savings, and set up automatic monthly transfers. Instead of the old "1% of your home's value" rule, many experts now suggest 2–3% a year. 2. Don't drain your savings at closing. Keep several thousand dollars in reserve rather than putting every dollar into the down payment or upgrades. 3. Invest in preventive maintenance. AC service, termite inspections, roof checks after storms, and hurricane prep catch small problems before they become expensive. See 10 Hidden Home Maintenance Tasks That Could Save You Thousands. 4. Know your home's systems and their ages. A 12-year-old water heater isn't an emergency today, but it signals an expense within a few years. Planning beats scrambling. Why Homeownership Still Makes Sense Despite the costs, homeownership remains one of the most powerful ways to build wealth, when you approach it wisely. Equity building: Every payment builds equity, and homes have historically appreciated over time. Stability and control: Renovate, paint, landscape, or add impact windows. It's your home, your way. Predictability: Rents have climbed about 31% over the past five years nationally.[7] With a fixed-rate mortgage, your principal and interest, typically the largest part of your payment, stay the same. Renters face increases on their entire housing cost. Lifestyle: Community roots, stability for your family, and the pride of owning something that's truly yours. A Better Way to Think About Affordability True affordability isn't the maximum a lender will approve. It's the amount that lets you sleep well at night, even when the water heater fails or insurance goes up. Smart buyers calculate affordability as mortgage + taxes + insurance + HOA + maintenance from the start. It might narrow your price range a little, but it gives you breathing room and peace of mind. Thinking about buying? I'll help you look beyond the list price, from realistic tax and insurance estimates to reading inspection reports as a budget plan. Book a free buyer consultation. First-time buyer? Start with 5 Easy Steps to Buying Your First Home and 5 Roadblocks to Affordable Homeownership, or take a HUD-approved homebuyer class. This article is for informational purposes only and is not financial, legal, or tax advice. Costs vary by home and location. Sources Bankrate: Hidden Costs of Homeownership Bankrate: Homeowner Regrets Survey NAHB: Property Taxes 2024 Matic: 2026 Home Insurance Predictions Realtor.com: Homeowners Associations 2024 Inman: Home Maintenance Costs Rise Rentec Direct: State of Rent 2025

Read More
Home Sellers Homeowners Investors

Can You Really Trust Online Home Estimates?

Nov 03, 2025

For millions of homeowners, checking their Zillow Zestimate has become as routine as checking a stock portfolio: a quick peek at your home's value, right at your fingertips. With 178 million monthly users and more than 100 million homes covered, the appeal is easy to understand. It's instant, free, and convenient. But here's a famous cautionary tale. Spencer Rascoff, Zillow's former CEO, sold his own home for about 40% less than its Zestimate.[1] Zillow itself describes the Zestimate as "a starting point" and says it is not an appraisal.[2] If the man who ran the company can be that far off, how accurate are online estimates for the rest of us? Relying on an automated number for your most valuable asset could be a mistake worth tens of thousands of dollars. As a Pricing Strategy Advisor (PSA), I help homeowners understand what their home is really worth. Here's how online estimates work, how accurate they are, what they miss, especially in South Florida, and why local expertise still matters. How Online Estimates Calculate Your Home's Value Online estimates come from Automated Valuation Models (AVMs), algorithms that crunch huge amounts of data in seconds.[3] Think of them as powerful calculators: impressive, but only as good as the information they're given. AVMs look at public records, tax assessments, recent comparable sales, and basic facts like bedrooms, bathrooms, and square footage.[4] For typical homes with plenty of recent nearby sales, they can produce a reasonable ballpark. But here's the key limitation: they never actually see your home. They're backward-looking, using what sold yesterday to guess what your home might sell for tomorrow. An algorithm knows you have three bedrooms. It doesn't know your primary suite has beautiful morning light, or that your roof is brand new. How Accurate Are They? AVM accuracy is often described as a median error rate: half of estimates land within that percentage of the actual sale price, and half miss by more.[2] The On-Market vs. Off-Market Divide Here's where most homeowners get tripped up: Platform Home Listed for Sale Home Not Listed Zillow ~1.9% median error ~7% median error Redfin ~2.0% median error ~7.7% median error Figures reported by Zillow and Redfin at the time of writing; accuracy varies by market and changes over time.[2][5] When a home is listed for sale, AVMs do surprisingly well. That's because they suddenly have fresh MLS data: professional photos, a detailed description, and the list price chosen by an agent. But if your home isn't on the market, which is probably the case if you're just curious, the typical error jumps to around 7–8%. What That Means in Dollars On a $400,000 home, a 7% error is about $28,000. On a $600,000 home, it's more than $40,000. And remember, that's the median. Half of estimates miss by even more. What Online Estimates Can't See Condition This is the algorithm's biggest weakness. It generally assumes your home is in average condition. Your newly renovated kitchen? Average. Your new roof? Average. On the flip side, an outdated bathroom, an aging AC, or deferred maintenance? Also average. Condition can make a huge difference between two otherwise identical homes. South Florida Blind Spots Here's what online estimates often miss in Miramar, Pembroke Pines, and across South Florida: Roof age: A new roof versus a 20-year-old roof can change a buyer's insurance costs, and their offer, dramatically. Impact windows and doors: These add real value and lower insurance, but public records often don't show them. HOA fees and special assessments: A high HOA fee or a pending condo assessment affects what buyers can afford. Lake and water views: Many neighborhoods here are built around lakes. A lakefront lot can be worth far more than a home a few doors away with no view. Location nuances: A quiet cul-de-sac versus a home backing onto a busy road, the Turnpike, or I-75. Same data, very different appeal. Unpermitted additions and conversions: Extra rooms or converted garages that aren't in public records can confuse the numbers, in either direction. Market Lag and Unique Homes Because AVMs rely on past sales, they lag behind fast-changing markets. And for custom, luxury, or unique homes, there often aren't enough similar sales for the algorithm to work well. The Solution: A Comparative Market Analysis (CMA) A Comparative Market Analysis (CMA) is the professional valuation a real estate agent prepares. It combines data with something algorithms can't provide: human expertise and local knowledge. What makes a CMA better: An in-person walk-through. Your agent sees the quality of your updates, the flow of your floor plan, the natural light, and the overall feel that shapes a buyer's reaction. With my renovation background, I can tell buyers, and you, exactly what your upgrades are worth. Street-level local knowledge. A local agent knows which streets and communities command a premium, how the season affects the market, and what buyers in your area want right now. Real, adjusted comparables. A CMA doesn't just list nearby sales. It adjusts them. For example: "Their kitchen had original 1990s oak cabinets; yours has modern shaker cabinets and quartz counters, so your home should command more. They have an older roof and accordion shutters; you have a new roof and impact windows, which adds value and lowers insurance." Online Estimate (AVM) CMA (Agent Valuation) Who provides it Automated algorithm Licensed local agent Sees your home? No Yes, condition is assessed Local detail Broad (ZIP code or area) Street, community, HOA, and micro-market Up to date? Can lag behind the market Reflects current conditions Typical accuracy ~2% listed, ~7–8% not listed Typically closer to the final sale price Pricing strategy None, just a number A tailored plan for pricing and positioning Best use Quick ballpark Real selling and buying decisions Why Pricing Right From Day One Matters An accurate price helps you avoid the two most expensive mistakes: Overpricing based on an inflated estimate. Your home sits, buyers wonder what's wrong, and you often end up selling for less than if you'd priced it right from the start. Underpricing based on a low estimate, which leaves money on the table. Your list price sets the first impression, and in real estate you rarely get a second one. When Online Estimates Are Useful For sellers: Use them as a conversation starter, never as your list price. Try my Instant Home Valuation tool for a quick ballpark, then let me prepare a personal CMA for the real number. For buyers: Use them to get a general sense of prices, but rely on your agent's analysis when making an offer. The algorithm doesn't know that three other buyers are submitting offers this weekend. Your agent does. Bottom Line: Technology Is a Tool, Not a Guide Online estimates are fun and convenient, but when your home isn't on the market, they can miss by 7–8% or more. That can mean tens of thousands of dollars. The blind spots around condition, location, and local details aren't minor glitches. They're gaps only local expertise can fill. "The final sale price was well above what I originally expected, simply because Natiesha knew how to position the home and guide the repairs properly." — Natalie S., Home Seller ⭐⭐⭐⭐⭐ Ready to know what your home is really worth? Request your free, personalized home valuation or book a seller consultation. I'll walk through your home, factor in today's market, and show you how to position it for top dollar. Related: Top 5 Things to Consider When Selling Your House · The Hidden Cost of Living in a "Well-Loved" Home Too Long This article is for informational purposes only. A CMA is not an appraisal. Accuracy figures are reported by each company and change over time. Sources Inman: Zillow CEO Sold Home for Much Less Than Zestimate Zillow: Zestimate Accuracy Rocket Mortgage: Automated Valuation Models Experian: What Is an Automated Valuation Model? Redfin: Redfin Estimate

Read More
Investors Home Sellers Home Buyers Homeowners

How to Spot Real Estate Scams (and Protect Your Investment)

Oct 10, 2025

Real estate scams are hitting more people than ever, and they're getting more sophisticated. According to the FBI, nearly 10,000 Americans reported real estate fraud in 2024, with losses of more than $173 million.[1] About one in four home buyers or sellers encounter suspicious activity during closing, and one in 20 become victims of wire fraud.[2] These aren't just traps for the inexperienced. They're professional operations that can fool seasoned investors and savvy consumers alike. Remote closings and digital communication have created new openings that criminals actively exploit. Whether you're a first-time buyer, investor, homeowner, or renter, here's how to recognize the most common scams, and protect yourself here in South Florida. 1. Wire Transfer Fraud: The Costliest Threat Wire fraud strikes at closing, when buyers are most vulnerable. Criminals hack or fake emails from real estate agents, title companies, or attorneys, then send fake wiring instructions that send your down payment to their account. The emails look official, use the right terminology, and create urgency around your closing deadline. Real estate wire fraud cost victims about $145 million in reported losses in 2023,[1] and typical losses run more than $70,000 per case.[4] For many buyers, that's their entire down payment. Once the money is sent, it's usually gone for good. Warning signs: Last-minute changes to wiring instructions, marked urgent Email addresses that are slightly off, like "titlle-co.com" instead of "title-co.com" Pressure to act immediately to avoid closing delays How to protect yourself: Always confirm wiring instructions by phone, using a number you already know is correct, such as one from your contract or the title company's official website. Never use a phone number from the email itself. Many brokerages now have clients sign a wire fraud acknowledgment.[5] If you suspect fraud, call your bank immediately and file a report with the FBI's Internet Crime Complaint Center (IC3.gov). Acting within 24–72 hours gives you the best chance of recovering funds.[5] 2. Rental Listing Scams: Too Good to Be True Rental scammers copy real listings, often homes for sale, and advertise them at below-market rent to collect deposits for homes they don't own. They create urgency ("lots of people are interested!") and usually claim to be out of town or overseas so they can't meet. Red flags: Rent that's much lower than similar homes in the area A "landlord" who can't meet in person or show the home Requests for payment before you've seen the property or signed a lease[7] How to protect yourself: Never send money for a rental you haven't seen in person. Verify ownership through the county property appraiser's website. In Broward, that's the Broward County Property Appraiser; in Miami-Dade, it's the Miami-Dade Property Appraiser. Never pay with wire transfers, gift cards, cryptocurrency, or payment apps. Homeowners: If your home is vacant or listed for sale, search online for fake rental ads using your address. 3. Title and Deed Fraud: Stealing Your Home In deed fraud, criminals forge documents, often a quitclaim deed with a forged signature, to make it look like they own your property. Then they may borrow against it, sell it, or rent it out. Vacant homes, vacant land, investment properties, and homes owned free and clear are prime targets, because fraud can go unnoticed for months. The FBI has reported a steady increase in quitclaim deed fraud,[8] and from 2019 to 2023, more than 58,000 victims reported $1.3 billion in losses to real estate fraud.[8] Warning signs: mail about a mortgage you didn't take out, property tax bills that suddenly stop coming, or unexpected foreclosure or transfer notices. How to protect yourself: sign up for free fraud alerts. Broward County: The Broward County Property Appraiser offers Owner Alert, a free service that emails you if a document changing your property's ownership is recorded. You just need your name, email, and property ID number. Sign up for Owner Alert. Miami-Dade and other counties: Many Florida county clerks offer similar free alerts. See the statewide list of property alert services. Title insurance gives added protection. An owner's policy is one of the best investments you can make at closing. If you own rental properties or land, sign up for alerts on every property you own. 4. Fake Buyers, Sellers, and Agents Fake buyers make attractive cash offers, then send a fake cashier's check for more than the deposit and ask you to wire back the difference. Seller impersonation has exploded. More than half of U.S. real estate agents (54%) encountered seller impersonation attempts in 2023.[9] Scammers pose as property owners, often of vacant land or rentals, and try to sell property they don't own.[10] Florida has seen many of these cases. Fake agents create phony profiles, sometimes using real agents' names and photos, to collect bogus fees. In one South Florida case, a scammer stole a real REALTOR®'s identity online and collected thousands of dollars from victims.[13] How to protect yourself: Verify any agent's license at MyFloridaLicense.com. Ask for photo ID and verify property ownership through public records. Meet in person or by live video whenever possible. Never share banking information or accept funds from someone you haven't verified. 5. Bait-and-Switch Schemes These scams hook you with a great deal, then change the terms: Rentals: The advertised home is suddenly "unavailable," but there's a pricier one instead. "We Buy Houses" offers: A high price up front, then a last-minute lower offer, or a contract quietly sold to another buyer. Some sellers end up with as little as 50% of market value.[6] Mortgages: A too-good rate that requires a large upfront fee, then a higher rate later, or a lost deposit. Get every offer in writing, avoid non-refundable upfront fees, and walk away when terms suddenly change. Thinking of selling to a "We Buy Houses" company? Talk to me first. You deserve to know what your home is worth on the open market. Get your home's value. Your Defense Strategy Work with licensed professionals. Use reputable agents, attorneys, and title companies, and verify licenses and reviews. Verify every identity with photo ID and independent sources. Protect your information. Use strong passwords and two-factor authentication, and never email sensitive financial data. Slow down. Legitimate deals don't require you to skip verification. Pay safely. Send wires only to verified escrow or title accounts. Never pay with cash, gift cards, or crypto. Monitor your property. Sign up for Owner Alert or your county's fraud alert service. Report fraud to local police, IC3.gov, and the FTC. Bottom Line Real estate scams exploit trust and urgency, but the warning signs are consistent: skipped safeguards, pressure, unverified identities, and deals that seem too good to be true. If something feels off, pause and verify. It's better to lose a "great deal" than to lose your savings. Planning to buy, sell, or invest? Working with an experienced local agent who knows the red flags is one of your best protections. Book a free consultation. Related: Ready to Buy or Sell a Home? Here Are 5 Key Factors in Choosing the Right Agent This article is for informational purposes only and is not legal or financial advice. If you suspect fraud, contact law enforcement and your financial institution immediately. Sources FBI IC3: 2024 Internet Crime Report National Cybersecurity Alliance: Common Real Estate Scams Rocket Mortgage: Real Estate Scams Eftsure: Wire Fraud Statistics National Association of REALTORS®: Wire Fraud MMBB: Unmasking Real Estate Scams FTC: Rental Listing Scams Florida Realtors: Quitclaim Deed Fraud on the Rise ALTA: Seller Impersonation Fraud NBC Washington: Vacant Land Scams Kiplinger: Protecting Your Home from Deed Theft FHFA: Fraud Prevention NBC Miami: Scammer Posing as Realtor Broward County Property Appraiser: Owner Alert

Read More
Home Buyers Home Sellers Investors

September Market Update: First-Time Buyers Finally Have the Power

Sep 05, 2025

As we head into fall 2025, the South Florida housing market is shifting in a way that puts first-time buyers back in the driver's seat. These changes are happening across the country, but I'm focusing on Miramar's 33027 ZIP code to show exactly what they mean for buyers right here at home. For years, renters and new buyers felt priced out by rising home values and worn down by bidding wars. Now, more inventory, longer days on market, and a rebalancing of supply and demand are creating opportunities that didn't exist a year or two ago. For buyers, especially first-time buyers, this turning point means one thing: leverage. Fewer Home Sales, But More Breathing Room for Buyers Nationally, sales are still below pre-pandemic levels.[2][3] Many would-be buyers remain cautious because of economic uncertainty and affordability challenges from higher mortgage rates and home prices.[4] As Lawrence Yun, Chief Economist for the National Association of REALTORS®, explains: "Home sales have been at 75% of normal or pre-pandemic activity for the past three years, even with seven million jobs added to the economy. Pent-up housing demand continues to grow, though not realized. Any meaningful decline in mortgage rates will help release this demand."[3] But change is in the air. More inventory and selective price reductions are drawing buyers back in. In 33027, homes are staying on the market longer [add: median days on market is now about ___ days, compared with ___ days a year ago]. That gives you time to make thoughtful decisions instead of rushing to beat a dozen competing offers. What it means for first-time buyers in 33027: The slower pace works in your favor. With less competition, you can shop with confidence, negotiate terms, and avoid the "panic buying" of 2021 and 2022. For sellers: Success comes from understanding today's buyer mindset and pricing to match current conditions. I'll help you analyze local trends and build a strategy that gets results. Mortgage Rates: Elevated but Stable Thirty-year fixed mortgage rates are hovering below 7%, and Yun expects them to average about 6.4% in the second half of the year.[6] That's far from the sub-3% pandemic rates, but it's becoming the new normal. As Realtor.com's Hannah Jones put it, "Persistently high mortgage rates mean affordability remains top of mind."[5] Monthly housing payments have more than doubled since the pandemic, driven by both higher prices and higher rates.[7] In response, many builders and sellers are offering concessions, like rate buydowns and closing cost assistance.[8] What it means for first-time buyers in 33027: Don't let rates scare you off. Use your negotiating power to ask sellers for help with closing costs or a rate buydown. If rates drop later, you may be able to refinance, but always buy based on a payment you can comfortably afford today. Sellers, take note: Offering a rate buydown or closing cost help can set your listing apart and widen your pool of qualified buyers. I can help you decide which incentives make sense and how to market them. Inventory Is Growing, and That's a Game Changer One of the biggest shifts in 2025 is the jump in housing supply. Here in 33027, more single-family homes are coming on the market [add: about ___ active listings compared with ___ a year ago, or ___ months of supply]. Nationally, the shift is dramatic: according to Redfin, there are now an estimated 33.7% more sellers than buyers, the widest gap on record.[9] Several factors are behind it. Return-to-office trends have cooled demand in some once-hot markets, affordability keeps many buyers on the sidelines, and more homeowners tired of waiting are choosing to list. Many major metros, especially in the South and West, are now considered buyer's markets. "The balance of power in the U.S. housing market has shifted toward buyers," says Redfin senior economist Asad Khan.[9] What it means for first-time buyers in 33027: More inventory means more choices. You're less likely to give up your must-haves just to get a home. Whether you want a starter single-family home or something with room to grow, your odds of finding it are better this season. For sellers: With more competition, presentation and pricing matter more than ever. My Eden Styled-to-Sell System helps your home stand out. Home Prices Are Softening, But Holding Long-Term Value After years of rapid growth, prices are coming back down to earth. National prices are flattening, with some softening in South Florida too. In 33027, values remain well above pre-pandemic levels, but the rapid increases have cooled [add: median sale price about $, compared with $ a year ago]. Newsweek reports that home values fell in more than half of U.S. states in the first half of 2025, especially across the Sun Belt.[5] Economists expect the national median home price to stay flat in the third quarter and dip about 1% year-over-year by the end of 2025.[8] Sellers are starting to accept that the sky-high sales from 2021 and 2022 are no longer the benchmark. Affordability is still a major hurdle. Households earning $75,000 a year can afford only about 20% of homes for sale, down from nearly half before the pandemic.[1] The ongoing housing shortage is expected to keep prices from dropping dramatically.[10] As finance expert Michael Ryan told Newsweek, "The housing market isn't crashing dramatically, more like it's finally coming back down to earth from a sugar high."[5] What it means for first-time buyers in 33027: Softer prices and motivated sellers are opening doors that were locked two years ago. Instead of bidding over asking, you may be able to buy at or even below list price. For sellers: The key is realism. "Gone are the days when you could slap any old price on your house and expect a bidding war," says Ryan.[5] Pricing strategically from day one is critical. As a Pricing Strategy Advisor, I'll help you find what your home is truly worth in today's market. Get your home's value. Why First-Time Buyers Should Act Now If you've been renting in Miramar and waiting for the "right time," this may be it: Less competition means less pressure to settle. More inventory means more choices. Negotiating power means you can ask for seller credits, repairs, or rate buydowns. As a first-time buyer, you're in a stronger position than you've been in years. Buying your first home can feel overwhelming, but you don't have to do it alone. This September, I'm presenting at the HUD-certified First-Time Homebuyer Workshop through the Housing Foundation of America to walk new buyers through the process, and show you how to make this market shift work in your favor. You can also start with 5 Easy Steps to Buying Your First Home and 5 Roadblocks to Affordable Homeownership. Sellers and Homeowners: Know Your Options If you're selling, your strategy should reflect today's market, not yesterday's highs. See Top 5 Things to Consider When Selling Your House. If you're a homeowner, now is a good time to decide whether to stay put, refinance, or use your equity to make a move. See Renovate or Relocate? 3 Questions To Help You Decide. The best decision is an informed one. Whether you're buying your first home, selling your third, or weighing your next move, I bring the local insight, negotiation skills, and market knowledge to help you succeed. Let's talk about your goals. Book a free consultation. This article is for informational purposes only and is not financial, legal, or tax advice. Consult the appropriate professionals about your individual needs. Sources NAR: Housing Affordability Gap Zillow: Home Value and Sales Forecast NAR: Existing-Home Sales MarketWatch: The Silver Lining in a Stalled Market Newsweek: Home Values Dropping in Half the Country NAR: Lawrence Yun at the 2025 REALTORS® Legislative Meetings NAR: 2025 Residential Economic Issues & Trends Forum (Yun Slides) Redfin: Home Price Forecast ResiClub: 500,000 More Sellers Than Buyers Realtor.com: 2025 Forum Slides (Danielle Hale)

Read More
Investors

Master Investor Series 5 of 5 | Want to Buy Rentals Without the Drama? DSCR Loans & More

Jul 30, 2025

Getting into real estate investing is exciting, but figuring out how to finance your first (or next) deal is where many people stall out. The good news? You have more options than you think. Over this series, we've covered why to invest, what to buy, how to protect your property, and how to grow your portfolio with 1031 exchanges. In this final part, let's talk about how to pay for it. We'll break down the DSCR loan, a powerful tool for rental investors, and cover other popular options: conventional loans, FHA 203(k), hard money, private money, and cash-out refinancing. Whether you're just starting out or scaling up, understanding your financing options is key to making smart moves. What Is a DSCR Loan? DSCR stands for Debt Service Coverage Ratio. It's a fancy way of asking: Does the property's rent cover its monthly housing costs? That means the mortgage payment, property taxes, insurance, and any HOA fees. Instead of qualifying you with W-2s or tax returns, DSCR lenders mainly qualify you based on the property's income. If the rent covers the monthly costs, you may qualify, even if you're self-employed or already own several properties. Example: If a property rents for $4,000/month and the total monthly payment (principal, interest, taxes, insurance, and HOA) is $3,200, the DSCR is 1.25 ($4,000 ÷ $3,200). Many lenders want at least 1.0, and a ratio of 1.2–1.25 or higher usually gets better terms. Why Investors Love DSCR Loans Imagine buying a rental without handing over a single pay stub or tax return. That's the appeal of a DSCR loan. It flips the traditional process by focusing on what the property earns, not your personal income. You'll still need a solid credit score, a down payment (often around 20–25%), and cash reserves. But the paperwork is lighter, and it's especially helpful for: Self-employed investors whose tax returns don't show their true income Multi-property owners who have hit the limits of conventional financing Buyers who want a faster, simpler process South Florida reality check: Here, insurance premiums and HOA fees can be high, and they count in the DSCR calculation. A property that looks profitable on rent alone may fall short once those costs are included. That's why I always run the full numbers with real insurance quotes and HOA figures before you make an offer. DSCR and other non-traditional lenders can also sometimes finance condos that conventional lenders won't, which matters here as many buildings work through Florida's newer condo safety requirements. Conventional Loans If DSCR loans are the cool, non-traditional cousin, conventional loans are the buttoned-up sibling who follows all the rules but offers great benefits to those who qualify. Conventional loans follow Fannie Mae and Freddie Mac guidelines, which means competitive rates and long-term stability. But they'll look closely at your income, debt-to-income ratio, employment history, and credit. They're a strong fit for investors with: Steady, documented income Strong credit Plans to hold the property long-term Bonus: Conventional loans can finance investment properties with 1–4 units, as long as you qualify. Investment properties usually require a larger down payment than a primary home. FHA 203(k) Loans Ever watch HGTV and think, "I could totally do that"? An FHA 203(k) loan might be your real-life gateway to renovation dreams. This loan lets you buy a fixer-upper and finance the repairs in one mortgage, with as little as 3.5% down for qualified buyers. The catch: you must live in the home as your primary residence, generally for at least a year. Savvy investors use this for house hacking: buy a 2–4 unit property, live in one unit, rent out the others, and build equity while your tenants help cover the mortgage. Learn more in Income Properties Are Trending, But Is Landlord Life for You? With my renovation background, I can help you estimate repair costs and spot properties where a 203(k) makes sense. Hard Money Loans When time matters and traditional lenders are dragging their feet, hard money lenders swoop in like the superheroes of real estate funding, though ones who charge higher interest. These loans are asset-based. They focus on the property and the deal more than your personal finances. They're a great fit for fix-and-flips and BRRRR projects (Buy, Rehab, Rent, Refinance, Repeat), and some can close in days rather than weeks. You'll pay higher rates and fees, and the loans are short-term, so have a clear exit plan: a sale or a refinance. For investors who need speed and flexibility, it's often worth it. Private Money Loans Private money is the secret handshake of real estate investing: funding from friends, family, or individual investors who believe in your deal, and in you. Private lenders don't follow rigid bank guidelines. You negotiate the terms directly, so it's all about relationships, trust, and opportunity. Private money can help when: You have a great deal but need fast funding Your credit isn't perfect You need creative terms for a unique deal Just remember: Mixing business and personal relationships can be tricky. Put everything in writing, and have a real estate attorney prepare or review the loan documents. Networking is one of the best ways to meet private lenders. It's one of the reasons I founded the Real Estate Investors Roundtable. Cash-Out Refinance Already own a property that has gained value? A cash-out refinance lets you tap that equity to fuel your next investment. You replace your current mortgage with a new, larger one and receive the difference in cash. You can use it to: Buy another rental property Fund renovations Build your cash reserves It's a favorite move for experienced investors who want to grow without bringing new money to the table. Just be mindful of closing costs, the new monthly payment, and the new interest rate. If you have a low rate on your current loan, run the numbers carefully. The Takeaway: Build Smart. Finance Smarter. Real estate investing is about making your money work for you, and the right financing can unlock serious growth. Whether you're drawn to the simplicity of a DSCR loan, the sweat-equity potential of a 203(k), or the speed of hard money, your strategy should fit your goals, your timeline, and your comfort with risk. There's no one-size-fits-all solution. But with knowledge, and the right team in your corner, you can choose the loan that turns potential into profit. Ready to explore your options, review an underperforming property, or run the numbers on your next deal? Book a free investor consultation or visit Invest With Natiesha. I can also connect you with trusted local lenders who specialize in investor financing. Let's grow your real estate portfolio with intention and strategy. The Complete Master Investor Series: Make Money in Your Sleep: Top 3 Reasons an Investment Property Will Work for You Kinds of Real Estate Investment Opportunities in South Florida Hurricane-Resistant Upgrades Unlocking Wealth with 1031 Exchanges Want to Buy Rentals Without the Drama? DSCR Loans & More (you are here) This article is for informational purposes only and is not financial, legal, or tax advice. Loan terms and requirements vary by lender. Consult a qualified mortgage professional. Sources Alcova Mortgage: DSCR Loans Griffin Funding: What Is a DSCR Loan? Newsilver: DSCR vs. Conventional Sammamish Mortgage: DSCR Loans Guide OfferMarket: DSCR vs. Conventional Mortgage CommercialRealEstate.loans: DSCR Explained HelloData.ai: Pros and Cons of DSCR Loans Investopedia: FHA 203(k) Loan Roofstock: Conventional Loans for Rentals Forbes: Cash-Out Refinance

Read More